
Enfuce runs the issuing. Pliant runs the card program.
Most partners building on Enfuce assemble the product themselves. With Pliant, it's already built. Credit included, expense management included, ready to go live in weeks.
Chosen by the companies reshaping how businesses pay


Why teams choose Pliant over Enfuce
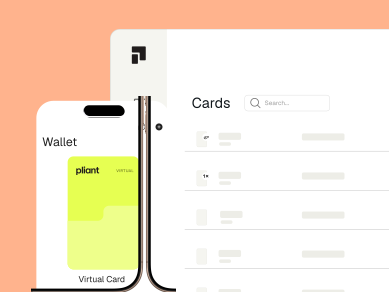
The card product your customers use, included
Card issuing, embedded credit, spend controls, receipt capture, approval workflows, and accounting integrations. All in one platform. No separate product build required.
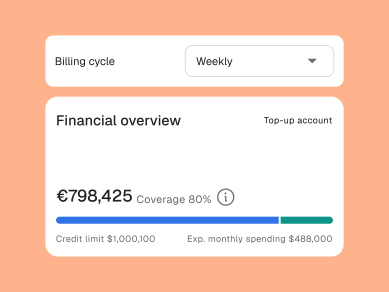
Credit that runs inside the platform
Get embedded credit lines across 30 EEA countries and the US. Limits, billing cycles, and repayment all run inside Pliant. Enfuce can process credit programs, but the lending comes from a partner bank you source and manage separately.
Expense management that plugs in, not bolts on
Many fintechs that issue through Enfuce run a separate expense tool alongside it. With Pliant, spend controls, receipt capture, approval flows, and ERP integrations are part of the platform. Your customers get the full picture from day one.

How Pliant and Enfuce compare
| Feature | Pliant | Enfuce |
|---|---|---|
| Card issuing | ✓ | ✓ |
| White-label product experience | ✓ Full card and spend platform | ✓ Card management app |
| KYC / AML compliance handled | ✓ | ✓ |
| Mastercard & Visa support | ✓ | ✓ |
| Virtual and physical cards | ✓ | ✓ |
| Native corporate credit cards | ✓ | Via partner banks |
| Multi-country EU card programs | ✓ | ✕ |
| EEA + UK coverage | ✓ | ✕ |
| Embedded credit lines across EEA | ✓ | ✕ |
| Credit risk handled in-house | ✓ | ✕ |
| Integrated expense management | ✓ | Partner-built or third-party |
| Spend controls & approval workflows | ✓ | Partner-built |
| Accounting integrations included | ✓ | ✕ |
| Turnkey product, no product layer to build | ✓ | ✕ |
| Card types | Prepaid, Debit, Credit | Debit, Prepaid, Credit (via partners) |
| Refinancing | Credit lines, Prefund | Partner-funded credit, Prefund |


Grow your business with your own card program
Design and launch your own program using our modular Cards-as-a-Service platform. Pliant provides the card issuing layer alongside the banking-as-a-service capabilities required to operate real-world embedded finance products: covering compliance and settlement.

Pliant versus Enfuce FAQ
With Pliant, the product your customers use is already built. KYC, compliance, cardholder experience, and admin tools are all included. Most partners go live in weeks. Enfuce handles the regulated issuing and processing layer well, but the cardholder product, admin tooling, and expense workflows are yours to design and launch on top. How fast you go live depends on how fast you build.
No. Spend controls, receipt capture, approval workflows, accounting integrations, and reporting are part of the platform. Enfuce is issuing infrastructure. The expense layer sits outside it. Many teams that issue through Enfuce integrate a separate expense tool to fill that gap.
Pliant owns the credit product end-to-end: native corporate credit cards with embedded credit lines across 30 EEA countries, with limits, billing cycles, and repayment all running inside the platform. Enfuce can process credit card programs technically, but the lending is funded and underwritten by a partner bank. A separate arrangement you set up and manage outside of Enfuce.
Pliant operates across 30 EEA countries under a single EMI license, with US expansion now live. Enfuce covers the EEA and UK under its Finnish EMI license and UK FCA authorisation. Strong European coverage, but no US offering.
Enfuce gives you regulated issuing and processing infrastructure. You design and build the product on top. Pliant gives you the complete card program: cardholder experience, admin tools, expense management, credit, and compliance all included. Both are legitimate models. The question is how much you want to own.
Ready to partner with us?
Click below to schedule a conversation with our Cards-as-a-Service team to discuss how Pliant’s CaaS can transform your product.